Weekly Thought
Print/PDF Print/PDF

Why Now for Ninepoint American Growth Fund: Shifting Leadership Favors an Active Approach

Key Takeaways
  • U.S. growth still has runway: Strong earnings and innovation support the outlook.
  • Market leadership may shift: Heavy tech concentration strengthens the case for active selection.
  • American Growth takes a different approach: High-conviction holdings, overweight Health Care and underweight Technology.

“The Business of America is Business”

“The business of America is business.” Calvin Coolidge said it a century ago, and it describes a country that is, above all, concerned with producing, buying, selling, and profiting. Today it still reads as a fair description of what drives the U.S. economy. There is no shortage of controversy about how America conducts its business right now. Yet through all of it, the engine keeps running - American companies keep finding ways to earn more, invest in new ideas, and adapt faster than their peers anywhere else.

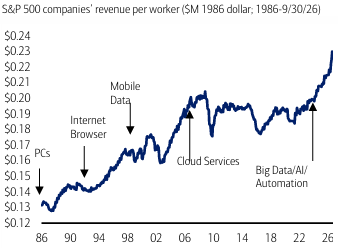
That pattern goes back a long way, from the assembly line to the personal computer, the internet, the smartphone, cloud computing, and now artificial intelligence. Each wave looked uncertain at first, and each eventually showed up as higher productivity, meaning more output for the same amount of work. That is what lifts profits and living standards over time. Corporate profits, not politics, remain the best explanation for why the U.S. is still the most dynamic and innovative economy in the world.

Figure 1 – U.S. Productivity Gains Over Innovation Cycles
Click for larger image
Source: Bank of America Merrill Lynch, as of October 2026

That innovative, profit-driven engine is the thinking behind the Ninepoint American Growth Fund, which we launched last week. The fund takes a high-conviction approach, concentrating on market leaders that stand to benefit from innovation or from the broader macro backdrop. It also raises a question we may well hear: why start a U.S. growth fund now? The answer lies in how the market looks today and where it may be headed:

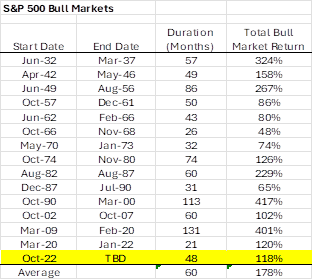
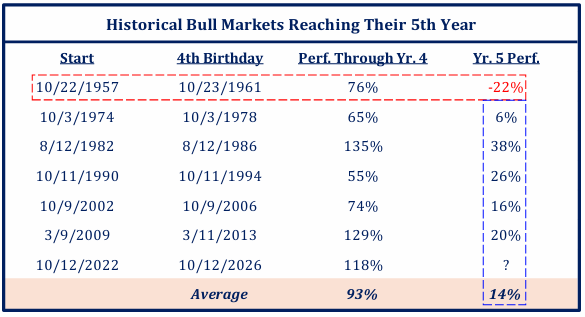
  • Current Bull Market Neither Old nor Extreme - Start with the bull market itself, which just celebrated its 4th birthday. Over those four years, the S&P 500 is up 118% from its October 2022 low. That may seem like a lot, but it is a more modest gain than the first four years of the bull markets of the 1980s and the 2010s. It also falls well short of the 178% average gain for all bull markets since the 1930s. In other words, by the standards of history, this rally has been strong but not unusual. It hasn’t been particularly long either. Five of the last seven bull markets continued into a fifth year, and returns in that year were generally solid, averaging 14%.
Market perspective for the week ahead.

Hear from Tony Genua, Sam Mitter and Jonathan Lo on the developments, investment ideas and market signals worth watching. A concise read for advisors, delivered every Monday morning.

Figure 2 – S&P 500 Bull Markets

Click for larger image
Source: Baird Strategas, as of October 2026
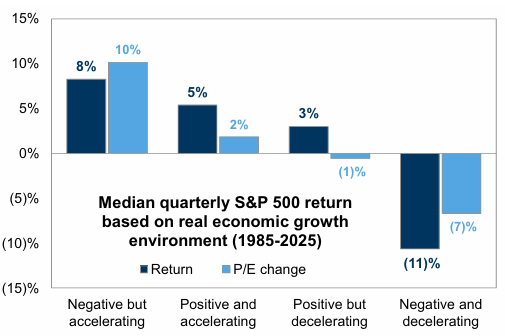
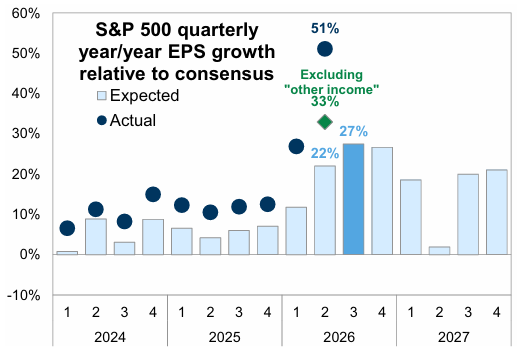
  • Earnings Growth is Exceptional (But Potentially Peaking) – When it comes to the most correlated factor with the stock market - earnings are still exceptional. Consensus expects S&P 500 earnings to grow 27% this quarter, a remarkable pace this far into a bull market. It may slow next year, though, as the easier comparisons fade and the pace of growth moves back toward more normal levels. That does not necessarily mean the bull market ends. Historically, periods of positive but decelerating earnings growth have still produced positive returns, just more muted ones, and those returns have been driven more by earnings growth than by rising valuations. There is also a point in favor of growth investing here. When growth becomes scarcer, investors have typically paid more for it, and growth stocks have tended to outperform in slowing-growth environments.

Figure 3 – Exceptional Earnings (LHS), Positive but Decelerating Earnings Performance (RHS)
Click for larger image
Source: Goldman Sachs, as of October 2026
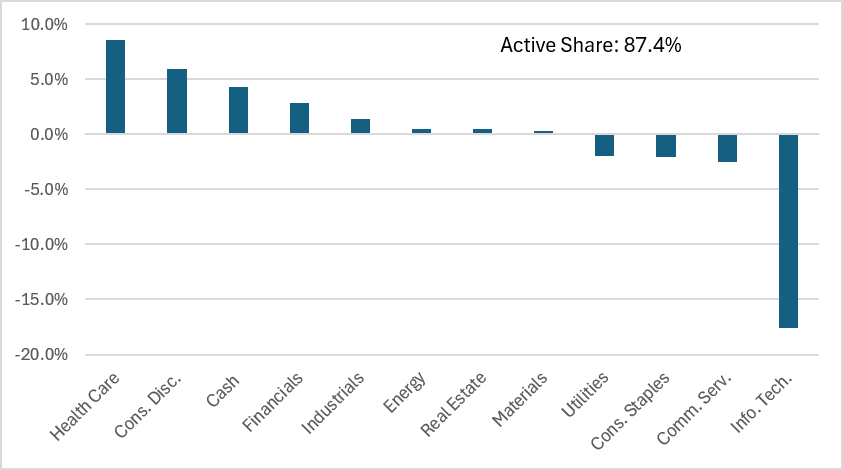
  • Therefore, This May Be Where Investors Need Something Different - If earnings growth is peaking, the market’s next leg may look different from the last one. Market leadership is always changing, and we may be at one of those inflection points. The concentration in AI and technology is hard to miss. Technology, together with Meta, Alphabet, and Amazon, now makes up about 50% of the S&P 500. The five largest names in the index, plus Micron and AMD, have accounted for 47% of the index’s return so far this year. Owning the index today means owning a very large bet on one theme. Our portfolio is built differently. With a high active share and a highly differentiated mix of holdings, we aim to generate alpha in a different way, by looking for emerging leadership trends before they become consensus. Today, our largest overweight is in Health Care and our largest underweight is in Technology.

Figure 4 – Ninepoint American Growth Fund – Relative Sector Weights vs. S&P 500
Click for larger image
Source: Ninepoint Partners and Bloomberg, as of October 2026

Owning the Business of America, Differently

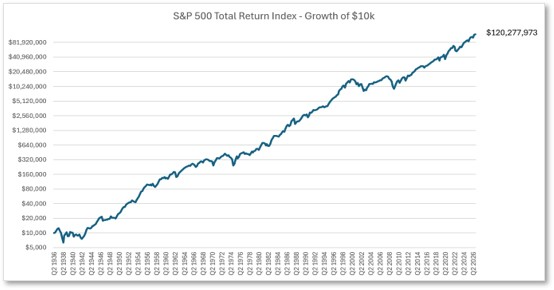
Nearly a century of results shows that when the business of America is business, owning a piece of it pays. A $10,000 investment in the S&P 500 total return index in 1936 would be worth more than $120 million today, through wars, recessions, inflation, and no shortage of controversy. The bull market is only four years old, earnings are still growing at an exceptional pace, and we have yet to fully reap the productivity benefits of the considerable spending to build out AI. But with so much of the market riding on a single theme, the next chapter may reward a different approach. That is why we launched the Ninepoint American Growth Fund: a high-conviction, actively managed way to own the best of American business, wherever the next leaders emerge.

Figure 5 – Growth of $10k in the S&P 500 Total Return Index (since 1936)
Click for larger image
Source: Morningstar, as of October 2026

Have a great week!

Tony, Sam & JLO

Tony Genua
Partner, Senior Portfolio Manager

Sam Mitter
Senior Portfolio Manager

Jonathan Lo
Portfolio Manager

Related Unboxed Ideas

View All
  • Q3 Earnings Preview – What We are Watching
    Q3 Earnings Preview – What We are Watching
    The stock market has held up well this year despite a growing set of risks. This includes rapidly rising yields - the U.S. 10-year Treasury yield rose 53 basis points in September alone and 82…
    Equities
  • The Muse is Loose
    The Muse is Loose
    In the 2008 film Iron Man, Tony Stark doesn't use his computer so much as talk to it. His AI assistant, JARVIS, runs his house, manages his schedule, handles his business and occasionally talks him…
    Equities
  • Rage Against The Machine
    Rage Against The Machine
    The people building the most powerful AI systems are now asking the industry to slow down. A week ago, Anthropic CEO Dario Amodei urged the industry to "pace the frontier," meaning ease off the race…
    Equities

The Ninepoint Global Select Fund is generally exposed to the following risks. See the simplified prospectus of the Fund for a description of these risks; Concentration risk; Credit risk; Currency risk; Cybersecurity risk; Derivatives Risk; Emerging markets risk; Exchange traded funds risk; Foreign investment risk; Halted trading of ETF Series risk; Inflation risk; Interest rate risk; Liquidity risk; Market risk; Regulatory risk; Securities lending, repurchase and reverse repurchase transactions risk; Series risk; Short selling risk; Small company risk; Specific issuer risk; Tax risk; Trading price of ETF Series risk.

Ninepoint Partners LP is the investment manager to the Ninepoint Funds (collectively, the “Funds”). Commissions, trailing commissions, management fees, performance fees (if any), other charges and expenses all may be associated with mutual fund investments. Please read the prospectus carefully before investing. Mutual funds are not guaranteed, their values change frequently and past performance may not be repeated. The information contained herein does not constitute an offer or solicitation by anyone in the United States or in any other jurisdiction in which such an offer or solicitation is not authorized or to any person to whom it is unlawful to make such an offer or solicitation. Prospective investors who are not resident in Canada should contact their financial advisor to determine whether securities of the Fund may be lawfully sold in their jurisdiction.

The opinions, estimates and projections (“information”) contained within this report are solely those of Ninepoint Partners LP and are subject to change without notice. Ninepoint Partners makes every effort to ensure that the information has been derived from sources believed to be reliable and accurate. However, Ninepoint Partners assumes no responsibility for any losses or damages, whether direct or indirect, which arise out of the use of this information. Ninepoint Partners is not under any obligation to update or keep current the information contained herein. The information should not be regarded by recipients as a substitute for the exercise of their own judgment. Please contact your own personal advisor on your particular circumstances. Views expressed regarding a particular company, security, industry or market sector should not be considered an indication of trading intent of any investment funds managed by Ninepoint Partners LP. Any reference to a particular company is for illustrative purposes only and should not to be considered as investment advice or a recommendation to buy or sell or should it be considered as an indication of how the portfolio of any investment fund managed by Ninepoint Partners LP is or will be invested. Ninepoint Partners LP and/or its affiliates may collectively beneficially own/control 1% or more of any class of the equity securities of the issuers mentioned in this report. Ninepoint Partners LP and/or its affiliates may hold short position in any class of the equity securities of the issuers mentioned in this report. During the preceding 12 months, Ninepoint Partners LP and/or its affiliates may have received remuneration other than normal course investment advisory or trade execution services from the issuers mentioned in this report.