Weekly Thought
Print/PDF Print/PDF

Beyond Silicon

Key Takeaways
  • AI leadership is broadening beyond chips.
  • Software is proving it can monetize AI.
  • AI is accelerating cybersecurity demand.

The Tape has its Say

Nvidia’s results were the obvious event of the week, and it was a good one. Management pointed to next year's growth as supply constrained at roughly 70%, well above consensus estimates and providing the market with visibility into next year for the first time. The market cap math – Nvidia gained 7% after its results which added $442 billion to its market value, representing more than 478 individual S&P 500 companies are worth in their entirety.

Fundamentally, there's not much to argue with (just like in previous quarters) – Nvidia provided the market with strong visibility into next year. But we pay attention to price as well as fundamentals, and the price action told a more complicated story. A print with this kind of demand visibility should have been a green light for the picks-and-shovels trade: memory, semi cap equipment, the rest of the supply chain, but that's not really what happened. Follow-through was thin, even with NVDA handing the market a clean growth signal. 

Instead, the money rotated into software, where the prints were also stellar. Salesforce delivered a strong beat-and-raise quarter, showed real traction with Agentforce, and announced a partnership with Anthropic that embeds CRM data directly into Claude.

It was another sign that software isn't dead - it's evolving. We're finally seeing tangible signs that AI can be a monetization event rather than simply a seat-destruction story. The original bear case was that AI commoditizes the application layer and destroys pricing power; Salesforce's print is starting to demonstrate the alternative — incumbent vendors using their proprietary data, workflows, and distribution to embed AI rather than getting disintermediated by it.

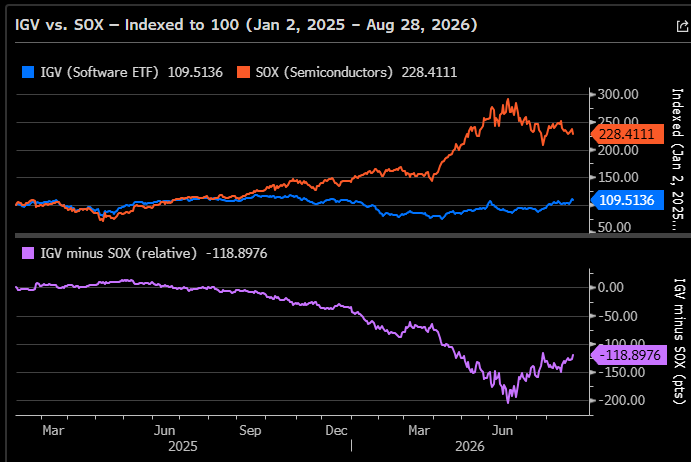
The cumulative effect: software (as represented by the iShares Expanded Tech-Software ETF - IGV) broke out to a new high on the year, recovering everything it had given back earlier. The software/semiconductors ratio pushed through a long-term trend line in the process. After two years of the hardware layer capturing the lion's share of AI enthusiasm, the love may be broadening out.

Figure 1 – iShares Expanded Tech-Software ETF (IGV) vs. Philadelphia Stock Exchange Semiconductor Index (SOX)
Click for larger image
Source: Bloomberg, as of August 28, 2026

Zero Day, Zero Rest

Helping the rally in software names was the cybersecurity space, where a string of strong results led by Crowdstrike helped security names make new highs. CrowdStrike delivered an outstanding quarter, signing a record $333 million in new subscription contracts — up 51% from a year ago and well above what analysts expected — pushing its total recurring revenue base to $5.84 billion, growing 25% year-over-year for the fourth straight quarter of acceleration. The big story was AI: CrowdStrike's new product that protects companies from AI-driven cyber threats nearly tripled in size in just one quarter, as the explosion of AI agents in the corporate world is creating a massive new wave of security demand that CrowdStrike is uniquely positioned to capture.

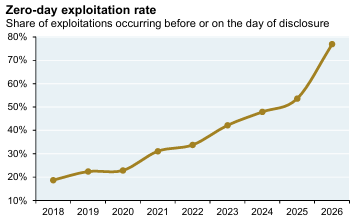
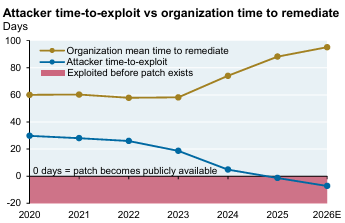
What's driving the urgency in cybersecurity right now is that hackers are getting faster at exploiting software flaws. A few years ago, attackers typically took about a year to exploit a newly disclosed vulnerability. Today that gap has shrunk to just one day. This is because advanced AI tools can now spot hidden software vulnerabilities that humans would never find. The catch is that the same AI that finds these flaws can also be used to weaponize them. Meanwhile, efforts to actually patch the code are falling behind: one analysis found AI is discovering new vulnerabilities 16 times faster than they're getting fixed. This puts most organizations in a constant state of playing catch-up, and the fact that CrowdStrike's AI-based security product nearly tripled in one quarter is a signal that the market is waking up to this urgency.

Figure 2 – Cybersecurity Urgency
Click for larger image
Source: JP Morgan, as of July 2026
Click for larger image
Source: JP Morgan, as of July 2026

Looking Down the Ice

Wayne Gretzky's line about skating to where the puck is going, not where it's been, gets overused in market commentary, but this week is a decent excuse to use it. The first two years of the AI trade rewarded owning the picks and shovels: chips, power generation, the physical buildout. That trade isn't necessarily over, but this week was a signal the market is starting to look further down the ice towards the companies that monetize AI and protect against it, not just the ones that build it. As with past market cycles of major tectonic shifts, skating alongside the winners is rewarding as long as they continue to anticipate where the puck is going.

Have a great week!

Tony, Sam & JLO

Tony Genua
Partner, Senior Portfolio Manager

Sam Mitter
Senior Portfolio Manager

Jonathan Lo
Portfolio Manager

Related Unboxed Ideas

View All
  • Coming Up for Air During the Dog Days of Summer
    Coming Up for Air During the Dog Days of Summer
    It's been a whirlwind of activities since I joined Ninepoint Partners just over a month ago. It's been a huge breath of fresh air working for a firm with great leadership, talented investment professionals, an…
    Equities
  • Trickling Down the Stack
    Trickling Down the Stack
    For the past two and a half years, playing the artificial intelligence (AI) theme has been an exercise in identifying the ultimate picks-and-shovels beneficiaries: semis, semiconductor fabrication, and massive power generation projects. Everything else in…
  • Focusing on the Next Shot
    Focusing on the Next Shot
    Fundamentals matter, but ultimately price is what is important. Fundamentals are the foundation, but the market is also a leading indicator, in the business of anticipating the fundamentals of the future, which means price can…

The Ninepoint Global Select Fund is generally exposed to the following risks. See the simplified prospectus of the Fund for a description of these risks; Concentration risk; Credit risk; Currency risk; Cybersecurity risk; Derivatives Risk; Emerging markets risk; Exchange traded funds risk; Foreign investment risk; Halted trading of ETF Series risk; Inflation risk; Interest rate risk; Liquidity risk; Market risk; Regulatory risk; Securities lending, repurchase and reverse repurchase transactions risk; Series risk; Short selling risk; Small company risk; Specific issuer risk; Tax risk; Trading price of ETF Series risk.

Ninepoint Partners LP is the investment manager to the Ninepoint Funds (collectively, the “Funds”). Commissions, trailing commissions, management fees, performance fees (if any), other charges and expenses all may be associated with mutual fund investments. Please read the prospectus carefully before investing. Mutual funds are not guaranteed, their values change frequently and past performance may not be repeated. The information contained herein does not constitute an offer or solicitation by anyone in the United States or in any other jurisdiction in which such an offer or solicitation is not authorized or to any person to whom it is unlawful to make such an offer or solicitation. Prospective investors who are not resident in Canada should contact their financial advisor to determine whether securities of the Fund may be lawfully sold in their jurisdiction.

The opinions, estimates and projections (“information”) contained within this report are solely those of Ninepoint Partners LP and are subject to change without notice. Ninepoint Partners makes every effort to ensure that the information has been derived from sources believed to be reliable and accurate. However, Ninepoint Partners assumes no responsibility for any losses or damages, whether direct or indirect, which arise out of the use of this information. Ninepoint Partners is not under any obligation to update or keep current the information contained herein. The information should not be regarded by recipients as a substitute for the exercise of their own judgment. Please contact your own personal advisor on your particular circumstances. Views expressed regarding a particular company, security, industry or market sector should not be considered an indication of trading intent of any investment funds managed by Ninepoint Partners LP. Any reference to a particular company is for illustrative purposes only and should not to be considered as investment advice or a recommendation to buy or sell or should it be considered as an indication of how the portfolio of any investment fund managed by Ninepoint Partners LP is or will be invested. Ninepoint Partners LP and/or its affiliates may collectively beneficially own/control 1% or more of any class of the equity securities of the issuers mentioned in this report. Ninepoint Partners LP and/or its affiliates may hold short position in any class of the equity securities of the issuers mentioned in this report. During the preceding 12 months, Ninepoint Partners LP and/or its affiliates may have received remuneration other than normal course investment advisory or trade execution services from the issuers mentioned in this report.